Late accounts cost a private company £150 to £1,500, doubled if last year was late too.

Try it freeFull version · $21 once →
What you get: The saved Excel workbook (6 inputs · 14 formulas): the same 10 lines plus a repeat-offence sheet that shows next year's Companies House penalty if you are late again (the doubling stays) and the…
Updated 2026-10-09 · ReadyStack
Late accounts cost a private company £150 to £1,500, doubled if last year was late too. A CT600 with a filing date on or after 1 April 2026 now costs £200 at one day late and another £200 at three months (was £100). Enter how late you are and see the total both offices will charge.
Who this is for: directors of UK limited companies and LLP designated members. Accounts are due at Companies House 9 months after the year end (6 months for a plc); the CT600 is due at HMRC 12 months after the end of the accounting period. Count a part month as a full month: 1 day to 1 month late = 1.
| Companies House band for one late year | - |
| Companies House late filing penalty | - |
| HMRC penalty for 1 day late | - |
| HMRC penalty for 3 months late | - |
| HMRC tax-geared penalty (10% at 6 months, 20% at 12) | - |
| HMRC CT600 late filing penalties | - |
| Total late filing penalties | - |
| Companies House penalty if filed 1 month later | - |
| HMRC fixed penalties at the old pre-April 2026 rates | - |
| Extra cost from the 1 April 2026 increase | - |
Everything updates as you type. Nothing is uploaded. This runs in your browser.
Full version — $21 once · the saved workbook with the repeat-offence sheet (next year's doubled penalty and the £1,000 third-late CT600 rate), one copy per company and year end.
The saved Excel workbook (6 inputs · 14 formulas): the same 10 lines plus a repeat-offence sheet that shows next year's Companies House penalty if you are late again (the doubling stays) and the CT600 penalties at the £1,000 third-late rate. Keep one copy per company and per year end, change the fig
One payment, one licence key for this tool. The key is shown right after payment.
Companies House 'Late filing penalties' guidance (updated 16 January 2026): private company or LLP £150 (not more than 1 month late), £375 (1-3 months), £750 (3-6 months), £1,500 (more than 6 months); public company £750 / £1,500
Buy the full version — $21I have a keyThis tool is 1 of 267 paid tools in English. All 267 with one key: Freelancer & Small Business Pass — $9.99/month · $79/year · Deadline reminders by email (free)
Need more than this one? ReadyStack Pass opens all 679 files and 561 full versions — $29/month or $199/year. See the Pass →
Paste this code into your page. It runs in your visitor’s browser and stays up to date. Nothing your visitors type is stored.
For businesses: your name and logo instead of ours, and each visitor’s result + e-mail in your inbox (only when they tick consent) — Pro from $19/month. See Pro →
· ReadyStack
Real numbers from this tool, line by line.
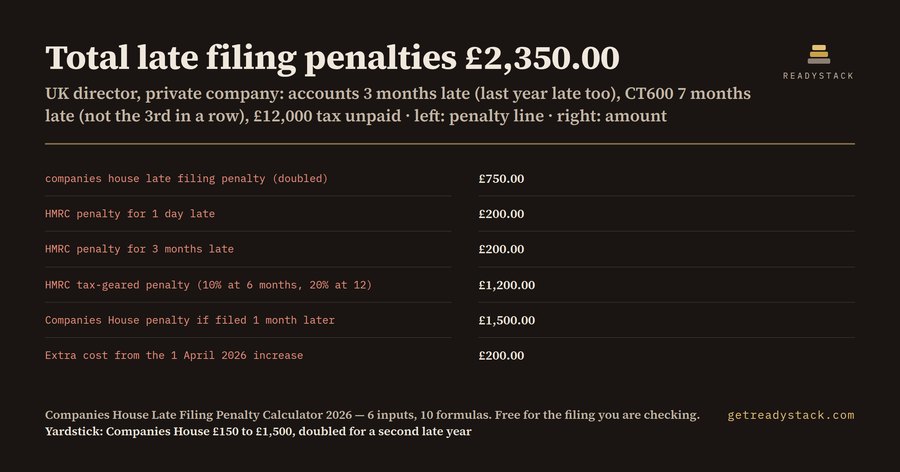
£2,350.00 in late filing penalties for one late year: a UK private company director whose accounts are 3 months late (last year's were late too) and whose CT600 is 7 months late, with £12,000 Corporation Tax unpaid.
| Line | Amount |
|---|---|
| Companies House band for one late year | £375.00 |
| Companies House late filing penalty (doubled) | £750.00 |
| HMRC penalty for 1 day late | £200.00 |
| HMRC penalty for 3 months late | £200.00 |
| HMRC tax-geared penalty at 10% | £1,200.00 |
| HMRC CT600 late filing penalties | £1,600.00 |
| Total late filing penalties | £2,350.00 |
Those seven lines come from two separate offices. Companies House charges for late accounts. HMRC charges for a late Company Tax Return (CT600). They arrive on different letters, and nobody adds them up for you.
Start with Companies House. A private company or LLP has 9 months from the end of its accounting reference period to deliver its accounts; a public company has 6 months. Miss that date and the penalty is automatic. For a private company or LLP it is £150 if the accounts are not more than 1 month late, £375 for 1 to 3 months, £750 for 3 to 6 months and £1,500 for more than 6 months. For a plc the bands are £750, £1,500, £3,000 and £7,500. If the accounts were also late the year before, the penalty is doubled. That is the Companies House guidance on late filing penalties, updated 16 January 2026. The director is personally responsible for delivering them.
Now HMRC. The CT600 is due 12 months after the end of the accounting period. For returns with a filing date on or after 1 April 2026 the fixed penalties doubled: £200 at one day late and another £200 at three months, where it used to be £100 and £100. If the return is late three times in a row, each fixed penalty becomes £1,000 instead of the old £500. At six months late HMRC estimates your Corporation Tax and adds 10% of the unpaid tax; at twelve months it adds another 10%. Those percentages did not change. Older articles and chatbots still quote £100.
Two more lines matter if you have not filed yet. If the accounts slip one more month, from 3 months late to 4, the Companies House penalty if filed 1 month later is £1,500.00, double the £750.00. The band boundary is the whole story: a few days can cost you £750. And of the £400 in fixed HMRC penalties, £200.00 is the extra cost from the 1 April 2026 increase.
Change the inputs and the answer moves. Put the accounts at 7 months late with no late year before, and the Companies House line becomes £1,500.00. A plc 1 month late pays £750.00 instead of £150. A CT600 13 months late, on a third late return in a row, with £50,000 unpaid, comes to £1,000.00 plus £1,000.00 plus £10,000.00 at 20%: £12,000.00 from HMRC alone.
How to count months: a part month counts as a full month. One day to one month late is 1. One month and one day is 2.
What to do today: file the accounts with Companies House and the CT600 with HMRC, because every band you cross costs more. If you had a reasonable excuse, appeal each penalty on its own. HMRC will only hear an appeal after the return has been filed.
The free calculator on our page has 6 inputs and 10 formulas and runs in your browser. Nothing is uploaded. The workbook adds 4 formulas on a repeat-offence sheet: next year's Companies House penalty if you are late again (the doubling stays), the HMRC penalties at the £1,000 third-late rate, the extra cost of that third late return, and the two-year exposure. In our example that last line is £4,700.00.
It adds up the two late filing penalties a UK company can get for the same year: the Companies House penalty for late accounts, using the statutory bands and the doubling for a second late year, and the HMRC penalties for a late CT600 at the rates for filing dates on or after 1 April 2026, including the 10% and 20% tax-geared penalties.
Directors of UK private limited companies, plcs and LLP designated members who have missed, or are about to miss, the accounts deadline at Companies House or the CT600 deadline at HMRC, and the bookkeepers who file for them. The director is personally responsible for delivering the accounts, so this is the number your company is about to be charged.
Companies House publishes only the accounts bands and HMRC publishes only the CT600 penalties. Neither page adds them up for your own months late, applies the doubling when last year was late too, or shows that a CT600 filed after 1 April 2026 now costs £200 at one day late, where older articles and chatbots still say £100.
The whole calculation on the page is free with no limit on runs: 6 inputs and 10 formulas giving the Companies House penalty, each HMRC penalty, the total, the cost of one more month at Companies House, and how much of the HMRC charge comes from the April 2026 increase. Your figures are computed in your browser and are not sent anywhere.
A saved Excel workbook with 6 inputs and 14 formulas: the same 10 lines as the page plus 4 on a repeat-offence sheet, showing next year's Companies House penalty if you are late again and the HMRC penalties at the £1,000 third-late rate. It is a one-time payment, not a subscription. Keep one copy per company and year end.
One question, answered by the person who built it. Your email only if you want the answer sent.
For a team or company: for an invoice with your company details, a quote or several licences, write to [email protected].
Your first gender pay report under Directive (EU) 2023/970Which report you owe, when it is due, and what a gap over 5 percent costs in back payFreeFull version $60
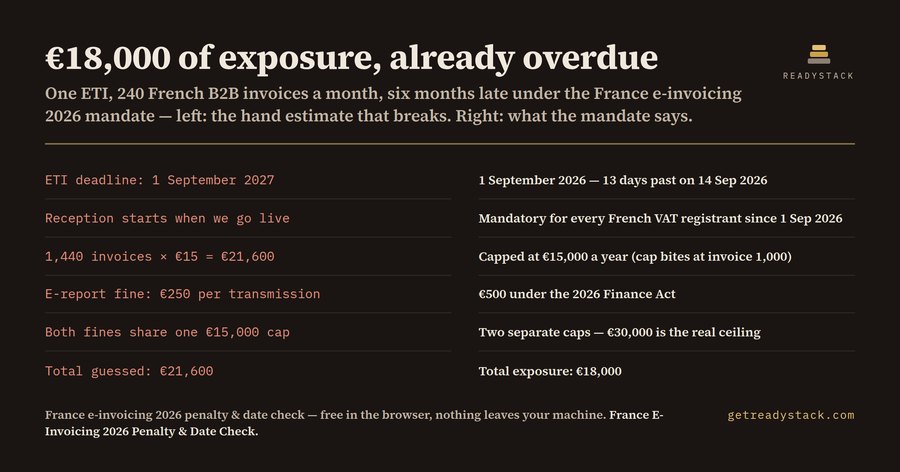
France e-invoicing 2026 — your date and your exposureYour own issuance date, your reception status, and what running late actually costs — €15 per invoice and €500 per missed e-report, each…FreeFull version $60
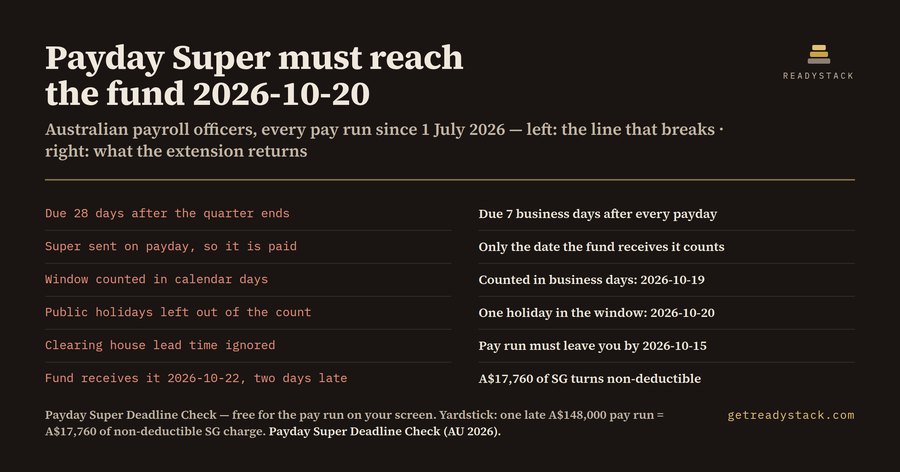
Payday Super: when must the fund have it?Counts the 7 business days from payday to the day the fund must have the money, and prices the deduction you lose when it lands late.FreeFull version $60
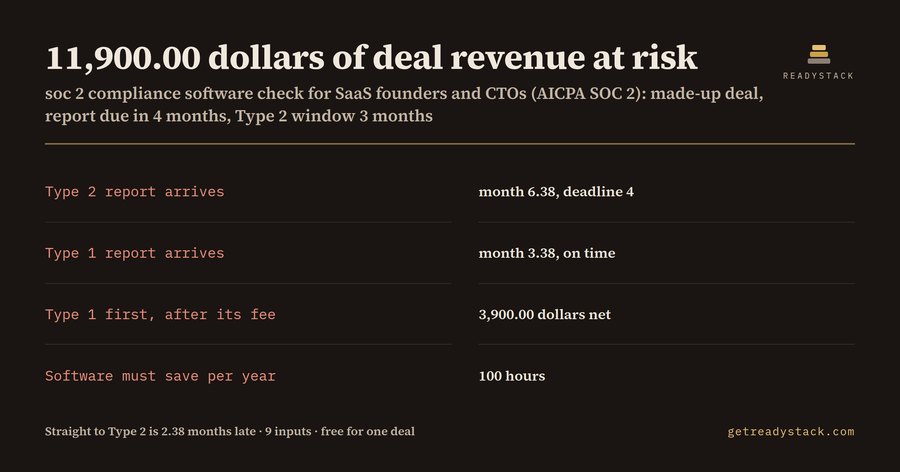
soc 2 compliance software check: Type 1 vs Type 2 report date against your customer deadlinesoc 2 compliance software check: when your Type 1 and Type 2 reports arrive vs your customer deadline, deal revenue at risk and first-year…FreeFull version $39
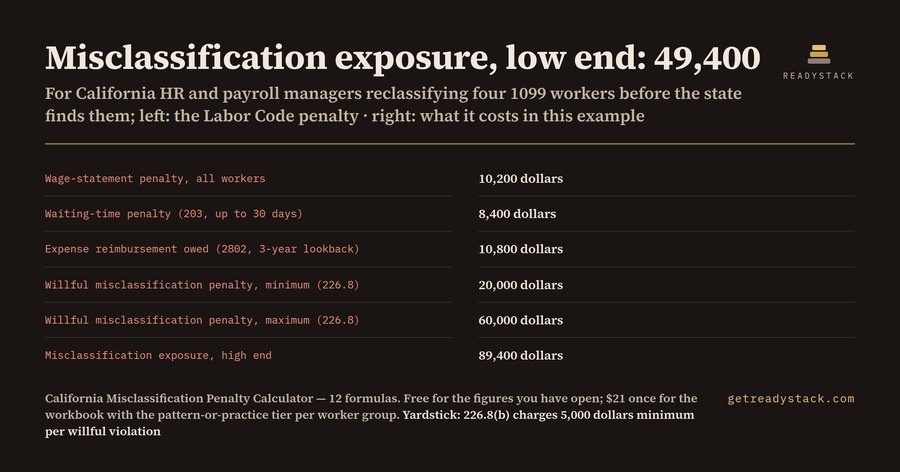
California Misclassification Penalty Calculator 2026California misclassification penalty calculator: Labor Code 226.8, 226(e) and 203 penalties plus 2802 expenses for your 1099 workers, low…FreeFull version $21
Date of death in, every 2026 federal estate deadline outEnter the date of death: the 9-month Form 706 due date, the Form 4768 extended date, the earliest closing-letter request and the…FreeFull version $60ReadyStack
Calculators, templates and deadlines for the rules that change every year — free in your browser.