Prices the last-month rule before the IRS prices it for you

Try it freeFull version · $60 →
Updated 2026-09-20 · ReadyStack
Prices the last-month rule before the IRS prices it for you
| Eligible months counted in 2026 | — | months |
|---|---|---|
| Month-by-month limit | — | $ |
| Limit that governs this election | — | $ |
| Employee + employer total | — | $ |
| Excess contribution for 2026 | — | $ |
| 6% excise per year on the excess | — | $ |
| Added back to income if the testing period fails | — | $ |
| Income tax + 10% additional tax on that add-back | — | $ |
| Total 2026 exposure | — | $ |
Free for the file open in your editor - no key, no limit. The workspace sweep and the report ask for a key.
Microsoft Edge Add-onsThe $60 key exports the audit as a .csv you keep and arms alarms for the Dec 1, 2026 and Dec 31, 2027 testing-period dates.
One payment, one licence key for this tool. The key is shown right after payment.
IRS Rev. Proc. 2025-19 sets the 2026 HSA limits ($4,400 self-only, $8,750 family, $1,000 age-55 catch-up). A CPA bills $150-$400 an hour in 2026 and a Form 1040-X amended return runs $200-$1,500 to unwind one wrong HSA year.
Buy the full version — $60I have a keyThis tool is 1 of 267 paid tools in English. All 267 with one key: Freelancer & Small Business Pass — $9.99/month · $79/year · Deadline reminders by email (free)
Need more than this one? ReadyStack Pass opens all 679 files and 561 full versions — $29/month or $199/year. See the Pass →
· ReadyStack
Real numbers from this tool, line by line.
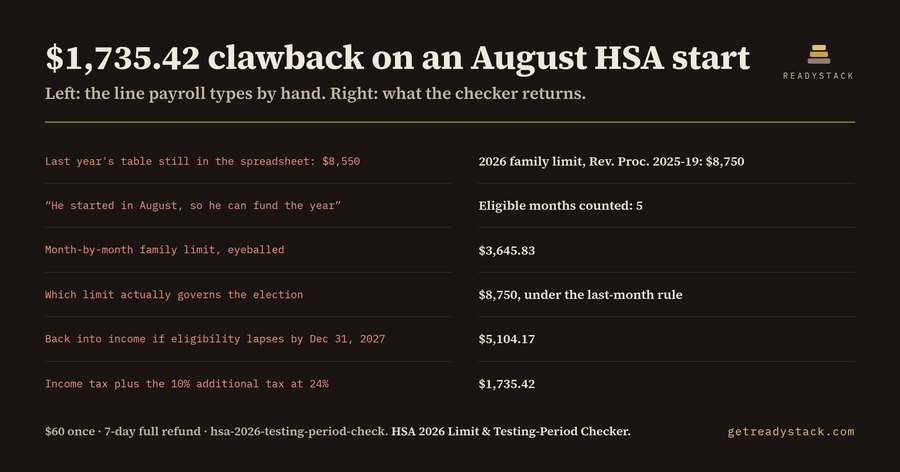
$1,735.42 of tax hangs on one line in a US payroll administrator's spreadsheet: the family HSA election of an employee whose high-deductible plan started on August 1, 2026.
He joined the family HDHP on August 1 and asks the obvious question: can he still put the full $8,750 into his HSA this year? Payroll checks the annual limit and says yes.
Payroll is right. That is the part that makes this expensive.
The last-month rule treats anyone HSA-eligible on December 1 as eligible for the whole year, so an August start does not cap the contribution at five twelfths. He may fund the full $8,750 for 2026.
What the rule attaches is a testing period. It runs from December 1, 2026 through December 31, 2027 - thirteen months. Stay HSA-eligible for all of it and nothing happens. Break it, and the difference between the full-year limit and the month-by-month limit stops being a contribution and becomes income.
Count the months he is eligible on the first day of the month: August through December. Five. The month-by-month family limit is $8,750 x 5/12 = $3,645.83.
The governing limit under the last-month rule is $8,750. The gap between them - $5,104.17 - is the amount at risk.
If eligibility lapses before December 31, 2027, that $5,104.17 goes into gross income for 2027 and carries a 10% additional tax on top of the ordinary tax. At a combined marginal rate of 24%, the bill is $1,735.42.
Nothing about that break has to be dramatic: a job change in March 2027, a spouse's PPO, or Medicare Part A at 65. Each ends HSA eligibility, and each is invisible to the payroll system that processed the 2026 election.
Run the same election the other way: eligible from January 1, but out of the HDHP on June 30. Without eligibility on December 1 the last-month rule does not apply, and the limit is the month-by-month one: $4,375.
The employee has already run $8,750 through payroll. The excess is $4,375, and an excess contribution draws a 6% excise tax for every year it stays in the account - $262.50 a year, on Form 5329, until it is withdrawn with its earnings.
Every free HSA calculator will tell you the annual limit. The year has to be right first: the 2025 limits were $4,300 self-only and $8,550 family, and IRS Rev. Proc. 2025-19 sets 2026 at $4,400 and $8,750. A stale table hands you the old numbers with the same confidence as the new ones.
Even with the right year, the annual limit answers a question nobody is asking. The question is whether this employee, with this start date and this plan for 2027, may fund the year - and what it costs if the answer is no.
Enter the coverage tier, the HDHP start date, the last 2026 month of eligibility, whether the employee reaches 55, the employee and employer dollars, the marginal rate, and whether eligibility survives all of 2027.
It returns the eligible month count, both limits, which one governs, any excess and its 6% excise, the testing-period add-back, the tax on it, and the total exposure. Every calculation is free, in the popup and on the web page, with no key, no cap and no watermark.
The $60 key does not unlock an answer. It exports the finished audit as a .csv you own, and it arms two browser alarms: the December 1, 2026 eligibility snapshot, and the December 31, 2027 testing-period close - the date that decides whether that $5,104.17 was a contribution or income.
A CPA bills $150 to $400 an hour in 2026, and a Form 1040-X to unwind one wrong HSA year runs $200 to $1,500.
It takes one 2026 HSA election - coverage tier, the date HDHP coverage started, the last month of eligibility, catch-up age, employee and employer dollars - and returns the month-by-month limit, the last-month-rule limit, which one governs, any excess and its 6% excise, and what the 13-month testing period costs if eligibility lapses.
US payroll and benefits administrators who process mid-year HSA elections, plus the CPAs and enrolled agents who clean them up in January. If you have ever had to decide whether an employee who joined the HDHP in August may fund the full $8,750, this is that decision, priced.
A general chatbot answers from whatever year's table it learned, and nothing in the answer tells you which year you got: 2025 was $4,300 and $8,550, 2026 is $4,400 and $8,750. Generic HSA calculators stop at the annual limit, so they never price the 13-month testing period, which is where the real money sits.
Every calculation is free, unlimited and key-free: proration, the last-month rule, the excise and the testing-period add-back, in the popup and on the web page. The $60 key changes the axis, not the answer - it exports the audit as a .csv you own and sets the two reminder alarms.
A CPA bills $150 to $400 an hour in 2026, and unwinding one wrong HSA year through a Form 1040-X amended return runs $200 to $1,500. One August-start family election carries $5,104.17 of testing-period add-back; at a 24% marginal rate that is $1,735.42 of tax.
One question, answered by the person who built it. Your email only if you want the answer sent.
Paste this code into your page. It runs in your visitor’s browser and stays up to date. Nothing your visitors type is stored.
For businesses: your name and logo instead of ours, and each visitor’s result + e-mail in your inbox (only when they tick consent) — Pro from $19/month. See Pro →
For a team or company: for an invoice with your company details, a quote or several licences, write to [email protected].
car flipping calculator | true profit, max offer, SE taxUnlicensed flippers pay sales tax when they buy the car, and the IRS takes 15.3% self-employment tax on 92.35% of the profit. In Florida, 3…Free
trading journal + wash sale tracker: all brokers, IRA, Form 8949, re-buy datesFinds the wash sales your 1099-B leaves out (other brokers, your IRA, call options), prints Form 8949 lines with code W and gives each…Paid
Commodity trading VAT check 2026: terminal market zero rateUnder VAT Notice 701/9, a futures trade between a listed market member and a non-member is zero-rated only while it does not lead to…FreeFull version $21
Market Dashboard 2026: Trader Tax Drag on US GainsFor US active traders filing single: short-term gains are taxed at 10-37% brackets, long-term at 0/15/20% (0% up to 49,450 dollars of…FreeFull version $21
UK Plastic Packaging Tax - quarter checkType your tonnage. Get the 10-tonne threshold answer, the bill at the 2026-27 rate of £228.82 a tonne, the late-filing penalty and the…FreeFull version $60
Section 174A catch-up: what is still stranded, and what releases itCheck U.S. domestic R&D from 2022–2024: compare 2025 catch-up routes, released deductions, tax value, and the gross-receipts test.FreeFull version $60
ADHD Planner for Adults: Missed Oct 15 Tax Deadline PenaltyADHD planner for adults who missed the Oct 15, 2026 tax extension: file by Dec 14 or the IRS $525 minimum late-filing penalty applies. Free…FreeFull version $21
Content Creator Planner 2026: Brand Deal Tax Set-AsideContent creator planner for US creators on 1099s: posting hours, brand-deal income and the 2026 self-employment tax to set aside before Jan…FreeFull version $21ReadyStack
Calculators, templates and deadlines for the rules that change every year — free in your browser.