Under the IRS proposed PRWORA rule, a taxpayer who is not a U.S.

Try it freeFull version · $21 →
Updated 2026-10-16 · ReadyStack
Under the IRS proposed PRWORA rule, a taxpayer who is not a U.S. citizen, U.S. national or qualified alien on the filing date loses the refunded portion of the child tax credit, EITC, AOTC and adoption credit. Treasury puts the 2026 average at $3,656. A false status declaration is a felony with a fine of up to $100,000 (section 7206).
$5,750 of this refund is barred: the refunded portion of the credits is a Federal public benefit and neither spouse is a U.S. citizen, U.S. national or qualified alien on the filing date.
| Affected refundable credits claimed ($) | $6,200.00 |
| Refunded portion = Federal public benefit ($) | $5,750.00 |
| Part that offsets tax, kept either way ($) | $450.00 |
| Return passes the PRWORA status test (1 = yes, 0 = no) | 0 |
| Declaration under penalty of perjury needed (1 = yes, 0 = no) | 1 |
| Refund if eligible ($) | $6,950.00 |
| Refund barred by the rule ($) | $5,750.00 |
| Refund after the rule ($) | $1,200.00 |
| Share of the refund lost (%) | 82.7 |
Everything updates as you type. Nothing is uploaded. This runs in your browser.
Full version — $21 once: the .xlsx Client Register for 25 returns (filing date, status drop-down, barred amount and declaration flag per client) with the Status Checklist sheet.
The $21 .xlsx, paid once, adds what one check does not keep: a Client Register for 25 returns with the filing date that first claims the credits, the status category picked from a drop-down list, the refunded portion, the dollars barred, the refund after the rule and the declaration flag per client,
One payment, one licence key for this tool. The key is shown right after payment.
BLS OEWS 2025: tax preparers median $26.40 an hour. Treasury's own estimate in Treasury/IRS proposed regulations, Federal Register, August 20, 2026 (FR Doc. 2026-16985): average refunded portion $3,656 in 2026; 200,000 to 700,000
Buy the full version — $21I have a keyThis tool is 1 of 267 paid tools in English. All 267 with one key: Freelancer & Small Business Pass — $9.99/month · $79/year · Deadline reminders by email (free)
Need more than this one? ReadyStack Pass opens all 679 files and 561 full versions — $29/month or $199/year. See the Pass →
Paste this code into your page. It runs in your visitor’s browser and stays up to date. Nothing your visitors type is stored.
For businesses: your name and logo instead of ours, and each visitor’s result + e-mail in your inbox (only when they tick consent) — Pro from $19/month. See Pro →
· ReadyStack
Real numbers from this tool, line by line.
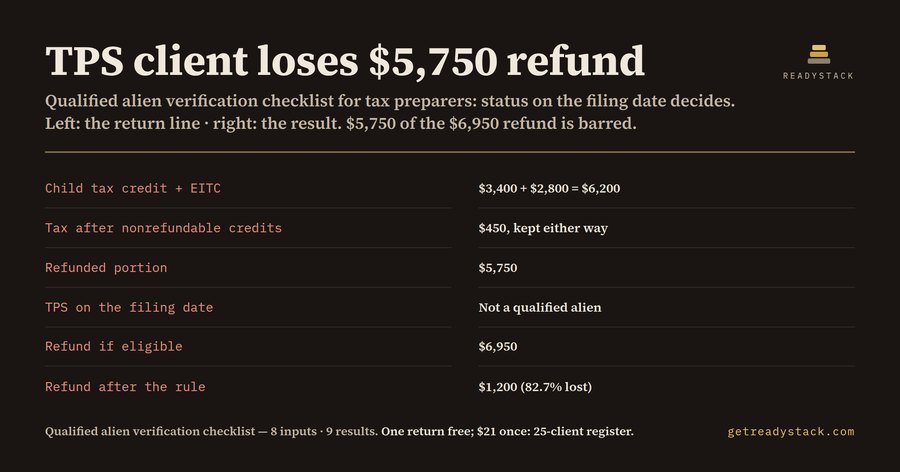
A TPS worker with two children loses $5,750 of a $6,950 refund under the IRS proposed rule, and tax preparers are the ones who have to catch it before filing.
Here is the return. Refundable child tax credit $3,400. Earned income credit $2,800. Tax after nonrefundable credits $450. Federal income tax withheld $1,200. The affected credits add up to $6,200. Take away the $450 of tax and the refunded portion is $5,750. Temporary Protected Status is not on the qualified alien list, so that $5,750 is barred. The refund falls from $6,950 to $1,200, a loss of 82.7%. The $1,200 of withholding still comes back.
On August 20, 2026 Treasury and the IRS published proposed regulations in the Federal Register (FR Doc. 2026-16985). They treat the refunded portion of four credits as a Federal public benefit under PRWORA: the adoption credit, the child tax credit, the American opportunity credit and the earned income credit. Only a U.S. citizen, a U.S. national or a qualified alien may receive it.
The refunded portion is the sum of those credits minus tax after nonrefundable credits. The part that offsets tax is kept either way.
8 U.S.C. 1641(b) lists lawful permanent residents, asylees, refugees, people paroled for at least 1 year, people whose deportation is withheld, conditional entrants before April 1, 1980, Cuban and Haitian entrants and Compact of Free Association residents. Section 1641(c) adds certain battered spouses and children.
TPS, DACA, nonimmigrant visas such as H-1B or F-1, and parole of less than 1 year are not on that list. A client can hold a work-eligible SSN and still fail this test. Tax software checks the SSN, not the status.
Status counts on the day the return that first claims the credit is filed. That can be an early, a late or an amended return. If a client first claims the credit while not qualified and gains status later, an amended return does not bring the refunded portion back. If the credit is first claimed on an amended return after the status change, it is allowed.
If one spouse is a U.S. citizen, U.S. national or qualified alien, the other spouse is treated as a qualified alien. An H-1B worker married to a U.S. citizen keeps the whole refund on a joint return.
When there is a refunded portion, the taxpayer or one spouse declares status under penalty of perjury on the form the IRS prescribes. Section 7206 carries a fine of up to $100,000 and up to 3 years.
Treasury estimates 200,000 to 700,000 taxpayers will be ineligible for tax year 2026, with an average refunded portion of $3,656. The rule is proposed to apply to taxable years ending on or after the date the final regulations are published.
Type the four credits, the tax and the withholding, then pick each spouse's status from the checklist. You get 9 results: affected credits, refunded portion, the part kept against tax, the status test, whether a declaration is needed, the refund if eligible, the dollars barred, the refund after the rule and the share lost. Nothing is uploaded.
It adds a client's refundable child tax credit, earned income credit, refundable AOTC and refundable adoption credit, subtracts tax after nonrefundable credits, and shows the refunded portion that the August 20, 2026 proposed rule treats as a Federal public benefit. Then it checks the client's status on the filing date against the 8 U.S.C. 1641 list and shows the dollars barred.
US tax preparers, enrolled agents and VITA volunteers who file returns for immigrant families claiming the child tax credit, EITC, American opportunity credit or adoption credit. Under the proposed rule they must ask whether the taxpayer, or one spouse on a joint return, is a U.S. citizen, U.S. national or qualified alien on the day the return is filed.
Because a work-eligible SSN is not the test. TPS holders, DACA recipients and nonimmigrant workers such as H-1B holders can have one, yet they are not on the qualified alien list in 8 U.S.C. 1641(b). Under the proposed rule they keep the part of the credits that offsets their tax but lose the refunded portion.
Free: the full check for one return, as often as you like, with no sign-up: all 9 results, the status checklist and the joint-return rule. Paid, $21 once: an .xlsx Client Register for 25 returns with filing date, status category, barred amount and declaration flag per client, plus the status checklist and timing rule as a sheet you keep in the file.
BLS OEWS 2025 puts the median tax preparer at $26.40 an hour. Treasury estimates the average refunded portion at $3,656 for 2026 and expects 200,000 to 700,000 taxpayers to be ineligible for it. One wrong status call on a return costs the client that refund, or exposes a false declaration under section 7206.
One question, answered by the person who built it. Your email only if you want the answer sent.
For a team or company: for an invoice with your company details, a quote or several licences, write to [email protected].
UK Plastic Packaging Tax - quarter checkType your tonnage. Get the 10-tonne threshold answer, the bill at the 2026-27 rate of £228.82 a tonne, the late-filing penalty and the…FreeFull version $60
179D grandfather check - deduction dollars that survive the 2026 sunsetDoes the project still clear the 2026-06-30 179D gate, and what is it worth on the 2026 rate table?FreeFull version $60
B2B services VAT location check: UK Notice 741A rulesA UK surveyor bills a US investor £15,000 for a London building: the land rule beats the B2B customer rule, so £3,000 UK VAT is due, and…FreeFull version $21
Content Creator Planner 2026: Brand Deal Tax Set-AsideContent creator planner for US creators on 1099s: posting hours, brand-deal income and the 2026 self-employment tax to set aside before Jan…FreeFull version $21
Mortgage Rates Calculator 2026: Your Real After-Tax RateMost mortgage rate calculators assume your interest is deductible.FreeFull version $21
Taxi VAT Calculator 2026: Private Hire Full Fare vs TOMSPrivate hire (minicab) operators lost TOMS on 2 January 2026: VAT is now 20% of the full fare. Type your fares and driver share to see the…FreeFull version $21ReadyStack
Calculators, templates and deadlines for the rules that change every year — free in your browser.