Standard method, all three de minimis tests and the annual adjustment date for one VAT period

Try it freeFull version · $60 →
Updated 2026-09-16 · ReadyStack
Standard method, all three de minimis tests and the annual adjustment date for one VAT period
| Standard method recovery rate | — | % |
|---|---|---|
| Rounding basis (PE30500) | — | |
| Residual input tax recoverable | — | £ |
| Total exempt input tax | — | £ |
| Exempt input tax per month (limit £625) | — | £ |
| De minimis result | — | |
| Input tax you can claim this period | — | £ |
| Input tax blocked by partial exemption | — | £ |
| Annual adjustment falls due | — |
A $60 key adds the things you keep and repeat: a CSV working paper of every input, test and verdict for the client file, and a browser reminder set for the return the annual adjustment is declared on.
One payment, one licence key for this tool. The key is shown right after payment.
A qualified UK accountant charges £100-£250 an hour in 2026 and a bookkeeper £25-£60 (Zmartly, Accountant Fees UK 2026); a fixed-fee partial exemption annual review has been tendered at £625 + VAT a year.
Buy the full version — $60I have a keyThis tool is 1 of 267 paid tools in English. All 267 with one key: Freelancer & Small Business Pass — $9.99/month · $79/year · Deadline reminders by email (free)
Need more than this one? ReadyStack Pass opens all 679 files and 561 full versions — $29/month or $199/year. See the Pass →
· ReadyStack
Real numbers from this tool, line by line.
£8,400 of input tax, blocked in a single quarter — that is what a bookkeeper at a UK charity with a trading arm finds the first time the partial exemption calculation is run properly instead of estimated.
Here is the period, as typed into the free calculator. Three months. Taxable supplies £418,500. Exempt supplies £181,500. Input tax directly attributable to taxable supplies £34,000. Input tax directly attributable to exempt supplies £1,200. Residual, or overhead, input tax £24,000.
The standard method in VAT Notice 706 splits that residual pot by the value of supplies: £418,500 over £600,000 is 69.75%. Most hand-worked schedules stop there and claim 69.75% of the residual. They should not. HMRC's PE30500 says the recovery rate is rounded up to the next whole percent, so the rate is 70% and £16,800 of the residual is recoverable rather than £16,740. The round-up is worth £60 on this period alone.
That rounding rule has a ceiling, and it is the part a chatbot will not tell you. Once residual input tax averages more than £400,000 a month you must round to two decimal places instead. Change the residual figure in the same period to £1,500,000 — £500,000 a month — and the rate stays at 69.75%. Rounding it up to 70% there would have overclaimed £3,750 in one quarter.
Then the de minimis test, which is where the £8,400 comes from. Total exempt input tax is the £1,200 directly attributable plus the £7,200 of residual the 70% rate does not recover: £8,400, or £2,800 a month. The limit is £625 a month on average — £1,875 a quarter, £7,500 a year — and it is an average, not a quarterly figure, which is the single most common thing people get wrong when they ask an AI assistant. There is a second condition as well: the exempt input tax must also be no more than 50% of total input tax. Both have to hold.
There are actually three routes through it: simplified test 1, simplified test 2 and the full de minimis test. You only need to pass one. This period fails all three, so the £8,400 is blocked and the claim for the quarter is £50,800 rather than £59,200. Shift the mix — taxable £480,000, exempt £20,000, residual £9,000 — and exempt input tax falls to £660, or £220 a month, test 3 passes, and the whole £43,300 is claimable. Same tool, opposite answer.
The last output is the one that costs money by being late. The quarterly calculation is provisional; every partially exempt business has to do a compulsory annual adjustment at the end of its partial exemption year. The year end follows your VAT stagger: 31 March, 30 April or 31 May. With a 31 March year end the adjustment is declared on the quarter ending 30 June 2026 and filed by 7 August 2026. A 30 April year end moves that to the quarter ending 31 July 2026, filed by 7 September 2026; 31 May moves it to 31 August 2026, filed by 7 October 2026.
Eight inputs, nine outputs, three de minimis tests, and no key. The calculation is free in full in the browser extension and on the web page — no cap, no watermark, nothing held back. A qualified UK accountant charges £100 to £250 an hour in 2026 and a bookkeeper £25 to £60; a fixed-fee partial exemption annual review has been tendered at £625 plus VAT a year. The paid layer is only what you keep and repeat: a CSV working paper of every input, test and verdict for the client file, and a browser reminder set for the return the adjustment is declared on.
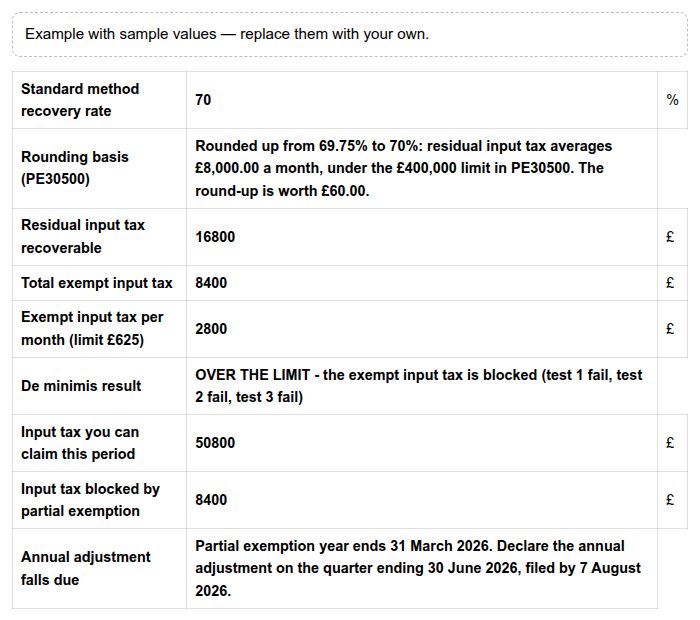
It takes one VAT period's taxable and exempt supplies and its three pots of input tax, applies the standard method in VAT Notice 706, rounds the recovery rate the way PE30500 requires, runs all three de minimis tests, and reports the input tax you may claim plus the date your annual adjustment falls due.
UK bookkeepers and in-house finance staff at partly exempt businesses: charities with trading arms, GP and dental practices, property landlords with a mix of opted and exempt rents, independent schools, insurance intermediaries and finance brokers. Anyone who files a VAT return where some input tax relates to exempt supplies needs this calculation every period.
General VAT calculators compute output tax on a sale; they do not attribute input tax at all. Chatbots routinely quote the de minimis limit as a quarterly figure, drop the separate fifty percent of total input tax condition, and miss the PE30500 rule that the recovery rate rounds up only while residual input tax stays under four hundred thousand pounds a month.
The whole calculation is free, forever, with no key and no cap: recovery rate, rounding basis, three de minimis tests, claimable input tax and the annual adjustment date. The twenty-nine dollar key adds a CSV working paper you keep in the client file and a browser reminder for the period the adjustment is declared on.
A qualified UK accountant charges one hundred to two hundred and fifty pounds an hour in 2026 and a bookkeeper twenty-five to sixty; a fixed-fee partial exemption annual review has been tendered at six hundred and twenty-five pounds plus VAT a year. This runs the period calculation in seconds and keeps the working.
One question, answered by the person who built it. Your email only if you want the answer sent.
Paste this code into your page. It runs in your visitor’s browser and stays up to date. Nothing your visitors type is stored.
For businesses: your name and logo instead of ours, and each visitor’s result + e-mail in your inbox (only when they tick consent) — Pro from $19/month. See Pro →
For a team or company: for an invoice with your company details, a quote or several licences, write to [email protected].
realtor calculator commission | split, cap, fees, SE taxYour commission check has no tax withheld: the IRS charges 15.3% self-employment tax on 92.35% of net earnings, and the estimated payment…Free
Construction Budget Spreadsheet UK 2026: CIS Deduction, Retention and Reverse Charge VATCIS takes 20% of the labour part of every payment (30% if you are not CIS-registered), and since 1 March 2021 the domestic reverse charge…FreeFull version $21
Market Dashboard 2026: Trader Tax Drag on US GainsFor US active traders filing single: short-term gains are taxed at 10-37% brackets, long-term at 0/15/20% (0% up to 49,450 dollars of…FreeFull version $21
UK Plastic Packaging Tax - quarter checkType your tonnage. Get the 10-tonne threshold answer, the bill at the 2026-27 rate of £228.82 a tonne, the late-filing penalty and the…FreeFull version $60
179D grandfather check - deduction dollars that survive the 2026 sunsetDoes the project still clear the 2026-06-30 179D gate, and what is it worth on the 2026 rate table?FreeFull version $60
Belgian B2B e-invoicing: fine exposure vs the 120% deductionWhat one PDF-only B2B invoice costs a Belgian seller now that the tolerance period is over — and what the 120% deduction gives backFreeFull version $60
Straight answers on your taxes, from a CPA who returns calls.A CPA firm in Asheville, North Carolina preparing individual and small business returns, monthly bookkeeping, payroll filings and…FreeFull version $49ReadyStack
Calculators, templates and deadlines for the rules that change every year — free in your browser.